The flood levy has caused most of the usual suspects on debts and deficits to come out and spruke their position, whether it's "increasing taxes is always bad" or "deficits are not really a problem for Australia". While my sympathies definitely lie with the latter rather than the former, I can't help but feel that we should have been building a rather large fiscal surplus over the past 20 years 'without a recession'.

There have been only three crosses into contraction since the recovery from the early 1990s recession. This is a remarkable turnaround from the situation between 1974 and 1992 when we had three recessions and 2 other downturns. Australia has had a remarkable turnaround since the early 1990s from the seemingly terminal decline of the 1970s and 1980s.
The reasonable fiscal position of the federal government in 2008-09 made a big difference for Australia's ability to ride out the GFC and more importantly not suffer the public debt problems that the Europeans and Americans are now faced with.
But let's not forget the continuing problem of private debt in Australia. As the following graphs clearly show, Australia remains vulnerable to changes in international financial supply.

After a little dip during the GFC, Australians have returned to the unprecedented debt levels of 2007-08. The question that always need to be asked is just how high can debt go? The answer will have a lot to do with external conditions. In an expanding global economy with Asian flourishing, many Australians could probably push their debt out even further. But if this occurs a day of reckoning will eventually come. A growth slowdown in Asia because of a political shock or just the effects of boom and bust may slow growth in Australia causing rising unemployment, more defaults on debts and so on.
The other issue is the graph on the right, which shows the percentage of annual income paid in interest. Now if the Reserve Bank of Australia (RBA) were to increase interest rates because of inflationary fears and you can bet they will if there is even the faintest whiff of price pressure, the pressure on household finances will increase proportionally. The pain of Queensland households has helped to reduce the pain of households in the rest of Australia.
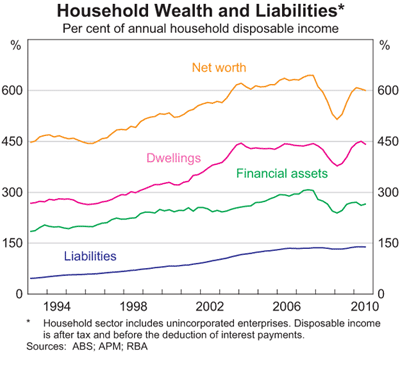
As the following graph shows, household net worth went down considerably during the GFC, while liabilities stayed relatively flat. While dwellings wealth has recovered financial assets have quite a deal to go before they get to pre-crisis levels.
The safe path would be for governments to encourage gradual deleveraging of households (and the private economy in general). Also important is a decreased reliance on foreign funding, perhaps through an increase in the super levy to 12 per cent as mooted in the Rudd government's aborted 2010 tax plans.
If we turn to inflation we can see why the RBA believes that price pressures almost got away from them before the GFC and why it now has a bias towards tightening. As the RBA governor said recently it's been rare that the RBA believes that it tightened too soon.

The high Australian dollar has also helped things on the inflation front. The following graph shows tradable and non-tradables inflation. Tradeables are those goods and services which can be exported or imported, while non tradables are not subject to export competition).

Tradable inflation has helped to keep overall inflation much lower and a higher exchange rate helps this as it makes the costs of imports lower.
There is no doubt that the Australian economy has performed remarkably since the early 1990s. This amazing overall performance (it's important to remember that not everyone has benefited) has been accentuated by the fact that the economy came through the GFC with little long-lasting damage when compared to most of Europe and the United States.
The following graphs on commodity prices make it entirely clear just how big a boost resource exports have given the Australian economy. Base metal prices have done well, but have some way to go before they match their peak, while rural goods have surpassed their previous highs.

Overall, however, commodity prices have matched their previous peak before the GFC and as the terms of trade shows are now approaching the post-war high associated with wool demand created by the Korean War.
The terms of trade is an index-measure ratio of the average price level of exports to the average price level of imports. It effectively reflects the capacity of a given quantity of exports to pay for a given quantity of imports, and provides an important indication of the strengths and weaknesses of the economic structure. A rising or falling terms of trade indicates the possibility of improving or declining living standards, because if what we sell earns relatively more than what we buy, we will be relatively wealthier. Because the terms of trade is a ratio, increases can be a result of export prices increasing at a greater rate than import prices, or export prices increasing while import prices are declining, or export prices declining at a slower rate than import prices. Of course, a rising terms of trade doesn’t stop us from buying more things than we sell, which we have made a habit of for much of our history! Improvements in the terms of trade are not reflected in GDP figures, but improvements do contribute significantly to increases in national disposable income.
While going into deficit was a necessary move by the Rudd government, the real question is whether the fiscal balance should have been in better shape before the crisis, given the mining boom and the long period of growth before the global financial crisis (GFC). Given Australia's recovery from the downturn and the increase in export prices the Gillard government certainly should be aiming to get a large surplus together sooner rather than later.
Being critical of the pro-deficit position is not an argument for less infrastructure spending, but for increased tax on super profits, especially in the mining sector, but perhaps also in the banking sector. Remember that Australia's mineral resources (whether you think we should be mining them or not) are non-renewable. Once they're gone, they're gone forever. They should be seen as the property of future generations as well as the present generation of Australians. Using taxes from mining profits to build infrastructure or to fund research into renewable energy sources makes sense on an inter-generational basis and would contribute to higher standards of living across the Australian population now and into the future.
If we look at GDP growth since the early 1990s it makes it even clearer that we should have built up a big surplus over time.

The reasonable fiscal position of the federal government in 2008-09 made a big difference for Australia's ability to ride out the GFC and more importantly not suffer the public debt problems that the Europeans and Americans are now faced with.
But let's not forget the continuing problem of private debt in Australia. As the following graphs clearly show, Australia remains vulnerable to changes in international financial supply.

After a little dip during the GFC, Australians have returned to the unprecedented debt levels of 2007-08. The question that always need to be asked is just how high can debt go? The answer will have a lot to do with external conditions. In an expanding global economy with Asian flourishing, many Australians could probably push their debt out even further. But if this occurs a day of reckoning will eventually come. A growth slowdown in Asia because of a political shock or just the effects of boom and bust may slow growth in Australia causing rising unemployment, more defaults on debts and so on.
The other issue is the graph on the right, which shows the percentage of annual income paid in interest. Now if the Reserve Bank of Australia (RBA) were to increase interest rates because of inflationary fears and you can bet they will if there is even the faintest whiff of price pressure, the pressure on household finances will increase proportionally. The pain of Queensland households has helped to reduce the pain of households in the rest of Australia.
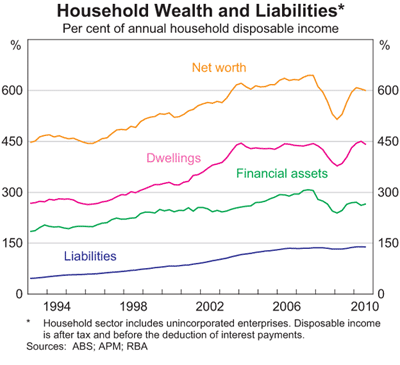
As the following graph shows, household net worth went down considerably during the GFC, while liabilities stayed relatively flat. While dwellings wealth has recovered financial assets have quite a deal to go before they get to pre-crisis levels.
The safe path would be for governments to encourage gradual deleveraging of households (and the private economy in general). Also important is a decreased reliance on foreign funding, perhaps through an increase in the super levy to 12 per cent as mooted in the Rudd government's aborted 2010 tax plans.
If we turn to inflation we can see why the RBA believes that price pressures almost got away from them before the GFC and why it now has a bias towards tightening. As the RBA governor said recently it's been rare that the RBA believes that it tightened too soon.

The high Australian dollar has also helped things on the inflation front. The following graph shows tradable and non-tradables inflation. Tradeables are those goods and services which can be exported or imported, while non tradables are not subject to export competition).

Tradable inflation has helped to keep overall inflation much lower and a higher exchange rate helps this as it makes the costs of imports lower.
There is no doubt that the Australian economy has performed remarkably since the early 1990s. This amazing overall performance (it's important to remember that not everyone has benefited) has been accentuated by the fact that the economy came through the GFC with little long-lasting damage when compared to most of Europe and the United States.
The following graphs on commodity prices make it entirely clear just how big a boost resource exports have given the Australian economy. Base metal prices have done well, but have some way to go before they match their peak, while rural goods have surpassed their previous highs.

Australia's two biggest exports iron ore and coal have increased enormously in value since a long period of stasis before 2000. China's increased steel use has been very good for Australia, but just how long prices can stay at these levels must be exercising the minds of miners in Australia. It should also be a subject of considerable concern for government in Australia given the 'untaxed' super-profits being made by our majority foreign-owned mining sector.
The terms of trade is an index-measure ratio of the average price level of exports to the average price level of imports. It effectively reflects the capacity of a given quantity of exports to pay for a given quantity of imports, and provides an important indication of the strengths and weaknesses of the economic structure. A rising or falling terms of trade indicates the possibility of improving or declining living standards, because if what we sell earns relatively more than what we buy, we will be relatively wealthier. Because the terms of trade is a ratio, increases can be a result of export prices increasing at a greater rate than import prices, or export prices increasing while import prices are declining, or export prices declining at a slower rate than import prices. Of course, a rising terms of trade doesn’t stop us from buying more things than we sell, which we have made a habit of for much of our history! Improvements in the terms of trade are not reflected in GDP figures, but improvements do contribute significantly to increases in national disposable income.
One thing that studying history has helped reinforce in my head is that good times don't last forever and that the history of the Australian economy is a history of boom and bust as the graph of the terms of trade makes clear. From the peak of 1950 until the late 1990s the terms of trade had been on a 50 year downward trend. It would be extremely optimistic to believe that we began a 50 year upward trend 10 years ago. But maybe I'm just being too negative!
All graphs from the RBA Chart Pack

